Key discrepancies — Archive 001
Examine the contradictions, shifting explanations, and unanswered questions revealed by the documentary record.
Questions the Record Raises
An evolving index of questions drawn from the filings, contemporaneous records, and discovery. Each links to a relevant source or comparison. As evidence develops, questions will be marked under examination, partially answered, or answered by the record.
- How did Stacie Branch come to swear that three vehicles had been repossessed when Interstate later admitted only one had been?Under examination
- What records did Branch examine before swearing that the original lawsuit's allegations were true?Under examination
- Why did Interstate attempt to withdraw its original reference to Christy in RFA 66?Under examination
- How could a July 2025 envelope establish mailing of a January 2026 letter?Under examination
- Who authorized the $700 sale of Moore's F-150, and what evidence supported that price?Under examination
- What did Samantha Jacobs know about the repossession allegations when the original complaint was prepared and filed?Under examination
- Why did Interstate continue using an address associated with returned mail, and what address records did its personnel review?Under examination
- What do the records reveal about the connection between Branch's interest in Moore's river property, his refusal to sell, and the conduct that followed?Under examination · Subject of Moore's allegations
- When was the January 8 letter actually created, approved, and sent, and what records establish those events?Under examination
- What contemporaneous valuation and repair information was available before Interstate approved the vehicle's disposition?Under examination
- What records and contractual provisions support Interstate's requests for attorney's fees and litigation expenses?Under examination
- Why were the Cadillac and older Ford described as repossessed when they remained in Moore's possession?Partially answered · Interstate later admitted they were not repossessed
- Is Interstate Credit Union’s lawsuit against Gregory Moore an exception to its historical collection practices—and if so, why?Under examination · Prior public-index searches did not identify a comparable state-court deficiency case in 13 surrounding Georgia counties; the search was not exhaustive.
An Unusual Lawsuit? Interstate’s Historical Court Record
Our earlier search across 13 surrounding Georgia counties did not identify another comparable state-court deficiency action by Interstate Credit Union. That limited search does not establish that no such case exists; not all court records are publicly indexed or included.
Question: Is this action different from Interstate’s usual collection practices? If so, who decided to pursue it and why?
Status: Under examination. Additional court records, institutional policies, and testimony may help answer the question.
Key discrepancies · Documentary evidence
Added October 25, 2026
A Letter from January 2026. An Envelope from July 2025.
Two documents. One written association. Six months that cannot be reconciled.


On October 7, 2026, correspondence from Samantha F. Jacobs, P.C. identified returned certified-mail documentation as relating to Interstate Credit Union’s January 8, 2026 letter.
The supplied envelope bears postal markings from July 2025—approximately six months before the date of the letter it was said to relate to.
The discrepancy is addressed in Moore’s Motion to Compel, and specific discovery requests seek the original electronic document and mailing records.
How can postal evidence from July 2025 establish mailing of a January 2026 letter?
October 7 correspondence · Read the office’s exact statement
“certified/returned mail documentation relating to the January 8, 2026 letter, including the certified-mail tracking information and returned-mail notation”
October 7, 2026 email signed by Denae Wireman, Legal Assistant, Samantha F. Jacobs, P.C. The envelope was already among Interstate’s produced documents (DOCS 79/81). This comparison does not establish who prepared the January letter or whether a separate January mailing occurred.
Interstate’s Account Keeps Changing
How did a sworn complaint allege repossession of vehicles Interstate later admitted it never repossessed—and how did the institution respond when that conflict entered the record?
Before the disputed repossession and lawsuit, Stacie Branch contacted Greg by text about buying his riverfront home. Greg says they had no prior personal relationship and he had not given her his private number. He declined a sale at that time. The Question of Motive explains why Greg connects that exchange to the institutional decisions examined here. The comparisons test what the participants knew from the beginning and how they responded afterward.
Updated October 15, 2026 · The key changes and the questions they raise, in one place.
A sworn repossession account contradicted by Interstate’s own admissions
Original account: The vehicles was repossessed on June 27, 2025.
Branch verified the complaint’s facts as true and correct. Later admissions: The Cadillac and 1998 Ford were never repossessed or sold. The amended complaint names only the 2015 Ford in its repossession allegation.
Interstate attempts to withdraw the Christy reference from RFA 66
September 22: The amount may be incorrect and is being worked on with Christy.
October 9: Interstate attempts to withdraw that reference as included in error, attributes the review to an omitted third loan, and says it did not intend to concede the claimed amount was incorrect. Greg challenged the revision. On October 27, the court preserved the binding admission about incomplete earlier documentation but did not establish the “may be incorrect” or “Christy” statements as conclusive admissions.
Repossession before the stated cure deadline
June 26 letter: Last day to cure: July 1, 2025. July 3 notice: Repossession occurred June 27—four days before that deadline. Receipt timing and the legal effect are not established by this comparison.
The amount demanded increases
Original complaint: $32,035.42. Amended complaint: $47,214.09, an increase of $15,178.67; additional relief is sought in both. Later tested principal and interest calculations reconcile, with a $9 understatement in one component. The remaining disputes include notification, disposition, expenses, and legal recoverability.
What was known before the lawsuit?
The source comparisons below test a central question: was the challenged conduct intentional from the beginning? The inquiry follows the contemporaneous collateral and account records into the preparation of the original complaint: who supplied the facts, what Stacie Branch reviewed before verifying them, and what Samantha Jacobs knew when the allegations were prepared and filed.
The Question of Motive explains the personal-property exchange that gives this inquiry its human context. Contradictions identify what needs explaining; source records and testimony must establish whether the explanation is mistake, knowing misrepresentation, or another account.
Knowledge and responsibility: Who supplied and checked the original sworn account? What did the responsible participants know? What decisions followed when contradictory information entered the record? Those questions are being investigated; the records do not yet establish intent or liability.
Exact quotations, source comparisons, and the parties’ explanations appear below. Read the full knowledge-and-responsibility inquiry.
The demand for legal fees has grown
Interstate Credit Union already seeks at least $5,000 in legal fees and expenses in the lawsuit it brought against Greg. It now asks that he also pay the cost of its opposition to his request for records.
In its October 12 filing, Interstate asked the court to make Greg pay its expenses and attorney’s fees for opposing his effort to obtain information he says remains missing. It also requested consideration of additional expenses and sanctions. No dollar amount was stated.
Access to relevant records is part of the legal process for examining a claim and defending against it. Georgia law gives both sides the right to seek relevant information that is not legally protected from disclosure. Greg is invoking that process—not asking for a special exception.
The financial demand now reaches beyond collecting the alleged debt and the cost of bringing suit. Interstate is asking Greg to bear the cost of its resistance to his efforts to examine the records behind its claim.
What needs explaining?
Also: the $5,000 legal-fee demand ↓
Greg’s account, with the supporting records below.
Interstate Credit Union sued Greg for money it says he owes. Greg disputes the claim. On September 29, 2026, Judge Shawn Z. Rowland granted Greg permission to file claims against Interstate. Greg then filed those claims in the same case. These are the three central questions in the record.
What is a deficiency? After a lender takes and sells property used to secure a loan, it applies the sale money to the debt. The amount it says remains unpaid is called a deficiency. Understanding that amount requires knowing what was sold, what money was received, and how the balance was calculated.
Interstate Credit Union said it repossessed three vehicles. I was still storing two that I had tried to surrender.
Greg’s account: I had tried to surrender the Cadillac and the 1998 Ford to Interstate Credit Union. Interstate Credit Union had not taken them, leaving me responsible for storing both vehicles. They remained in my possession when the lawsuit described them as repossessed.
The opening complaint identifies three vehicles and alleges, “The vehicles was repossessed on June 27, 2025.” Interstate’s later responses state that only the 2015 Ford was repossessed and admit that the other two were never repossessed or sold.
Why it matters: The question reaches back to the preparation of the lawsuit: who supplied the three-vehicle account, which collateral records were checked, and what Branch knew when she verified it. The later admissions make that original decision process central to the inquiry.
Opening complaint · CEO’s sworn verification · Letter reporting the later admissions
Interstate Credit Union said the amount might be wrong. Then Interstate Credit Union added $15,178 more.
The original claim was $32,035.42. A later response, quoted in Greg’s September 23 letter, said that amount “may be incorrect.” The amended claim rose to $47,214.09—an increase of $15,178.67.
Why it matters: The figures explain the increase; the inquiry asks who assembled and reviewed the original demand, what supported it at filing, and why the institution’s explanation later changed. Later arithmetic checks narrow the dispute without resolving legal recoverability.
Original amount · Reported uncertainty about the calculation · Pleading addressing the amended amount
Interstate Credit Union sold my truck for $700.
AI-colorized illustrations based on photographs supplied in discovery. Colors are estimated and some fine details may differ from the source photographs. Displayed views crop out the scanned-page margins. The originals are linked below each view.
See the other four truck photographs below ↓


Four more views of the F-150


Source: photograph pages 255–259 of Interstate’s production. Photograph dates have not been established. The September 23, 2026 letter, Greg requests missing discovery records · A001-007, reports a $700 private sale and $700 credit in the reviewed production.
Greg’s September 23 letter reports a $700 sale and credit for the 2015 Ford. It also says he had not located an accounting or worksheet in the reviewed production that reproduced the original $32,035.42 claim.
Interstate Credit Union’s own J.D. Power worksheet used 226,707 miles, while its own title record contained a historical odometer reading of 63,819 miles—a difference of 162,888 miles. The higher worksheet input produced a $7,260 mileage deduction. The historical title reading is not proof of the mileage on the sale date; the provenance and accuracy of the higher input remain disputed. See the truck →
Why it matters: The sale raises a sequence of decisions: who supplied the mileage and condition information, who recommended and authorized the disposition, and what was checked before the resulting deficiency was pursued. The $700 credit is documented; valuation, disposition, and legal recoverability remain disputed.
The accounting requested · The disputed balance and requested relief
The case is ongoing. These questions compare identified records; they are not court findings. The detailed comparisons below show dates, source availability, and what remains unresolved.
Interstate Credit Union is demanding that I pay $5,000+ in legal fees.
Interstate Credit Union’s President and CEO, Stacie Branch, supplied the sworn verification accompanying its original complaint. Samantha Jacobs represents Interstate in the lawsuit. Alongside the claimed debt, Interstate’s original and amended complaints request $5,000 in legal fees. On October 12, Interstate went further: it asked the court to make Greg pay its lawyers for fighting his effort to obtain records behind the claim it brought against him. No additional dollar amount was stated.
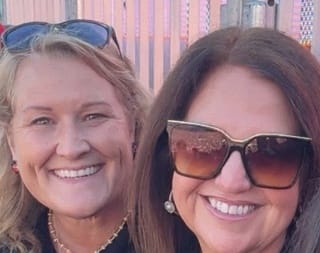
Left in photograph
Right in photograph
Source: screenshot of a Facebook post dated November 2, 2025, tagging Samantha Jacobs Tyre and Stacie Bowen Branch. Cropped to focus on the two identified people; faces and expressions are unaltered.
The $5,000 is a request in the lawsuit, not an award by the court. Greg disputes the claimed debt and seeks the records supporting the fee request.
Read the fee request in the original complaint →
Read the CEO’s sworn verification · Amended complaint record
These questions were also reported to regulators
Greg sent reports to Georgia’s Department of Banking and Finance (DBF) and the National Credit Union Administration (NCUA). Who those agencies are, what they do, and the two public summaries. These are Greg’s submissions, not agency findings.
Archive 001 follows Interstate Credit Union’s civil case against Greg. Follow three comparisons through the documentary record: which vehicles were repossessed, how the amount claimed changed, and what accounting support was requested.
Reading rule: These are comparisons of statements in identified records. A pleading states a party's position; correspondence records what its author communicated; a court order establishes the decision it actually makes.
Interstate Credit Union said it repossessed three vehicles. I was still storing two that I had tried to surrender.
Original statement — March 18–19, 2026
Interstate Credit Union’s original complaint identifies a 2003 Cadillac DeVille, a 1998 Ford F-150, and a 2015 Ford F-150. Paragraph 11 states: “The vehicles was repossessed on June 27, 2025.” Stacie Branch, identified in the filing as Interstate Credit Union’s President/CEO, signed the accompanying sworn verification on March 18; it was filed with the complaint on March 19.
Read Interstate’s original complaint · A001-001 and Stacie Branch’s sworn verification · A001-002.
Later response — reported September 22–23, 2026
The September 23 deficiency letter reports that Interstate's September 22 discovery responses state the Cadillac and 1998 Ford were not repossessed and only the 2015 Ford was repossessed. The September 29 counterclaim pleading also records the Defendant's position concerning those responses.
Read Greg requests missing discovery records · A001-007 and Greg’s amended answer and counterclaims · A001-012.
The experience behind the comparison: Greg says he had attempted to surrender the Cadillac and the 1998 Ford to Interstate Credit Union and remained responsible for storing them because Interstate Credit Union had not taken them.
Why it matters: The original repossession account was presented with the CEO’s sworn verification. Comparing it with the later admissions tests the factual basis available before filing and identifies the people and records needed to explain the contradiction.
What differs: The opening pleading's three-vehicle repossession account differs from the one-vehicle account reported in these later cleared sources. This comparison does not establish anyone's intent or a court finding of wrongdoing.
Source availability: The complete Interstate’s responses to requests for admission · A001-005, and Interstate’s responses to requests for records · A001-006, remain withheld pending publication review. The public trail here runs through the cleared derivatives identified above, rather than reproducing those held source files.
Interstate Credit Union said the amount might be wrong. Then Interstate Credit Union added $15,178 more.
Opening complaint — March 19, 2026
Interstate Credit Union alleged $32,035.42 in damages, with separate requests for legal fees, court costs, interest, and other relief. The complaint derivative reports two components: $6,209.70 and $25,825.72.
Source: Interstate’s original complaint · A001-001.
Discovery account — reported September 23, 2026
The deficiency letter references a response stating that complete documentation supporting the $32,035.42 calculation had not been produced, the amount may be incorrect, and it was being worked on with “Christy.” This is what the letter reports from the response, not a separately published full response.
Source: Greg requests missing discovery records · A001-007.
Amended demand — September 25, 2026
The cleared September 29 pleading derivative describes the September 25 amended complaint as alleging at least $47,214.09.
Source: Greg’s amended answer and counterclaims · A001-012. The full Interstate’s amended complaint · A001-008, remains withheld pending publication review.
Why it matters: The increase needs a documented basis, alongside an explanation of the earlier calculation. Counsel’s September 7 position can be read in sequence with the later records; it does not itself establish that the balance was wrong.
Arithmetic check: $6,209.70 + $25,825.72 = $32,035.42. $32,035.42 + $15,178.67 = $47,214.09. These sums reconcile the figures quoted here; they do not establish the contractual basis, accuracy, or recoverability of those amounts.
Interstate Credit Union sold my truck for $700.
What the September 23 letter records
The letter reports a $700 private sale and $700 credit in the production, and says its author had not located a single accounting or worksheet reproducing the $32,035.42 figure. It asks for balances, proceeds, expenses, adjustments, credits, and the account and contractual basis connecting them to the claimed deficiency.
What the later pleading requests
The September 29 pleading disputes that a lawful deficiency has been established and demands proof of the components of the amended amount.
What remains a documentary question: How do the underlying records connect the collateral disposition, proceeds and credits, account balances, and adjustments to the amount claimed? A record reported as not located in reviewed production is not the same as a finding that no such record exists.
Sources: Greg requests missing discovery records · A001-007 and Greg’s amended answer and counterclaims · A001-012.
Follow the sequence
March opening complaint and verification → May Answer → September discovery responses and deficiency letter → amended complaint → order granting leave and counterclaims.
The Chronology preserves the dates. The Document Index identifies the individual sources and release states. Court grants permission to file counterclaims · A001-011 establishes procedural authorization to file; it is not a decision on the truth of the counterclaim allegations.
How to Read · Documentary Method
Submit a correction or source question
Corrections and updates
Prepared October 2, 2026. Comparisons will be updated when a newly cleared source or verified event changes the record. Material corrections will identify what changed and when.
Read the exchanges in context
The Labor Day exchange and September discovery correspondence preserve what each sender actually communicated. The later service emails identify attachments; the emails themselves do not reproduce the attachments’ detailed grounds.
From the original collateral account to the amended complaint
The original complaint identifies three vehicles as collateral: the 2003 Cadillac DeVille, the 1998 Ford F-150, and the 2015 Ford F-150. The comparison below preserves the documents’ own wording, including the original grammar.
| Date and source | Exact documentary language | What the record shows |
|---|---|---|
| March 19 — original complaint, page 2, ¶11 · Source record | The vehicles was repossessed on June 27, 2025. | The plural allegation follows the complaint’s identification of the three vehicles. |
| Original complaint, page 2, ¶12 · Source record | After repossession, the collateral was disposed of in accordance with applicable law. | A general disposition assertion; the sentence does not separately name each vehicle. |
| March 18 — Branch verification, page 1 · Source record | the facts alleged in the foregoing COMPLAINT are true and correct. | Branch’s sworn verification adopts the complaint’s facts; her actual knowledge is a separate question. |
| September 22 — response to RFA 4, page 1 · Source record | Plaintiff neither admits nor denies the allegation contained in paragraph four (4). Plaintiff is unsure as to the allegation in Paragraph 11 of the Complaint and states that only the 2015 Ford was repossessed. | The response states that only the 2015 Ford was repossessed. |
| September 22 — RFA 8 and response, page 2 · Source record | Request: Admit that the Cadillac was not repossessed by Plaintiff on any date. Response: Plaintiff admits the allegation contained in paragraph eight (8). | Express admission concerning the Cadillac. |
| September 22 — RFA 9 and response, page 2 · Source record | Request: Admit that Plaintiff has never sold the Cadillac. Response: Plaintiff admits the allegation contained in paragraph nine (9). | Express admission concerning sale of the Cadillac. |
| September 22 — RFA 21 and response, page 3 · Source record | Request: Admit that the 1998 Ford was not repossessed by Plaintiff on any date. Response: Plaintiff admits the allegation contained in paragraph twenty-one (21). | Express admission concerning the older Ford. |
| September 22 — RFA 22 and response, page 3 · Source record | Request: Admit that Plaintiff has never sold the 1998 Ford. Response: Plaintiff admits the allegation contained in paragraph twenty-two (22). | Express admission concerning sale of the older Ford. |
| September 25 — amended complaint, page 3, ¶16 · Source record | The 2015 Ford F-150 was repossessed on June 27, 2025. | The amended repossession allegation expressly names the 2015 truck. |
| Amended complaint, page 3, ¶17 · Source record | After repossession, the collateral was disposed of in accordance with applicable law. | The general lawful-disposition assertion remains. |
The change in the repossession wording is documented. Why the original account was made, who supplied or reviewed the information, and what they actually knew remain subjects of discovery. The comparison does not itself prove knowledge, intent, or liability.
The monetary claim also changed
The original complaint requested at least $32,035.42, plus interest, court costs, and at least $5,000 in litigation expenses. The amended complaint requested at least $47,214.09 with the additional relief. Its stated components are $15,178.67, $25,825.72, and $6,209.70. The last two totals are unchanged from the original complaint; the added component accounts for the $15,178.67 increase in the pleaded total.
Sources: Original Complaint · Stacie Branch verification · First RFA responses · Amended Complaint · RFA 66 motion and plaintiff's revised response.
These quotations were checked against the original records. The complete discovery responses and amended complaint retain their existing publication holds; selected quotations do not release those files.
Repossession before the stated cure deadline
Two notices concerning the 2015 Ford place the stated repossession date before the last day offered to cure the default.
| Record | Exact language |
|---|---|
| June 26, 2025 cure letter Production page DOCS 152 | IF THE AMOUNT NOW DUE OF $2,222.20 IS PAID BY THE LAST DAY TO CURE THE DEFAULT(S), WHICH IS 07/01/2025, THE CREDIT UNION WILL NOT EXERCISE ITS RIGHTS UNDER THE LOAN AGREEMENTS AND APPLICABLE LAW, AND THE CONTRACT MAY BE CONTINUED AS THOUGH PAYMENTS WERE NOT LATE. |
| July 3, 2025 pre-sale notice Production page DOCS 153 | The above referenced property was repossessed by Interstate Credit Union on June 27, 2025. |
The stated June 27 repossession occurred four days before the July 1 cure deadline. The question is how Interstate reconciles the recovery date with the opportunity described in its June 26 letter.
This comparison establishes the dates and wording in the produced records. It does not establish when Greg received the cure letter, whether the stated payment was made, or how the court will resolve the issue.
Source summary: cure and recovery notices · Related inquiry into knowledge and responsibility.
October 27 court ruling on Admission No. 66
The court preserved Interstate’s binding September 22 admission that its prior documentation was incomplete. It did not declare the separate “may be incorrect” and “Christy” wording conclusively admitted. The original responses, subsequent revisions, and dispute remain part of the documentary record. Read Judge Rowland’s signed ruling →
How Interstate revised its accounting response
On September 22, Interstate said the original amount “may be incorrect and is being worked on with Christy.” On October 9, it attempted to withdraw the Christy reference and explained the earlier review as concerning an omitted third loan. The identity and role of the person originally named, and the basis for the two explanations, remain questions in the documentary inquiry.
In its September 22 response to RFA 66, Interstate said the original amount may be incorrect and is being worked on with Christy.
Its October 9 revised response attributes the review to an omitted third loan and states: Plaintiff withdraws the reference to “working with Christy,” as that statement was included in error and has no relevance to the claims or calculations at issue.
The revised response also says the earlier response was not intended to concede that the claimed amount was incorrect. Greg filed a motion asking the court to determine the legal effect of that revision.
These statements are presented in sequence, with Interstate’s explanation and Greg’s challenge both identified. On October 27, Judge Rowland ruled that Interstate’s admission about incomplete previously provided documentation remains binding. The court did not treat the “may be incorrect” wording or the “Christy” reference as conclusively established admissions; they remain available for evidentiary evaluation.
September 22 discovery responses · October 9 revised response · Greg’s challenge to the revision.
October 11 — Later accounting review
Greg’s September 23 letter records what he had then located in the production. Later review has identified loan histories, contracts, sale documentation, and the $700 credit. Tested principal histories and interest calculations reconcile; one tested component understates the calculation by $9. Those checks do not decide disputes about notification, collateral disposition, expenses, or the amount legally recoverable.
The earlier letter remains available as a dated record. The later review narrows the accounting questions rather than treating every calculation as unexplained.